Showing posts with label finance. Show all posts

Tuesday, April 30, 2019

Fundraising ideas for Destination Imagination Global Finals

My daughters got lucky and fell into a great Destination Imagination program at our town. Not everything has run perfectly, but we have been extremely blessed and are now preparing to head to globals for the second time. A large part of that preparation right now is fundraising. The move to Kansas City seems to have made it especially more expensive this year. My daughter's team seems to have had a lot of success with fundraising this year so I wanted to share some tips from what I've seen (mostly from the outside):


  • Year-round fundraising. Ideally, fundraising occurs all year round and not just during the month or so between states and globals. The problem with this is what to do with the funds if you don't actually make it to globals? Our town has a non-profit that supports the DI program. Money accumulates with that organization so that it's there when a team does make it to globals. That's the theory, although I realize there's a lot of details in the implementation which I do not know.
  • GoFundMe. We got tipped off to this during our first trip to globals and we're using it again. The site does take a fee off the top, but it's worth the cost in the ease of use. A lot of successful fundraising has to do with reducing friction for those who want to donate, and GoFundMe does a great job of that.
  • Business sponsorships. Our town has a culture of working with local businesses to provide support for various things. It really does take a village. I realize that demographics and culture might make this a less viable option. Remember that it's a culture that has to start sometime and somewhere, so why not with supporting DI? You can even sweeten the deal by mentioning how you will display your gratitude for the fundraising. 
  • Business fundraisers. This is another side of the previous item, but maybe more palatable for businesses. We have a number of restaurants in the area that will do proceed sharing nights. For example, 20% of the proceeds from orders at Ginger during April 23rd were donated to our town teams heading to Global Finals. I admit that the owners of the restaurant have a daughter on one of the teams, but I've seen other organizations do similar things with a local pizza place. It makes sense: you drive traffic to their restaurant and so everybody wins.
    Women of Science
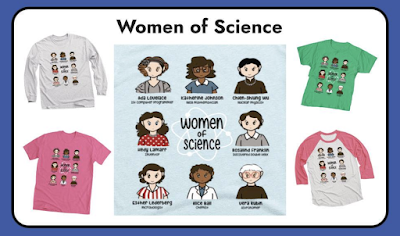
  • Bonfire. We did a t-shirt fundraiser for the first time this year and it took off like gangbusters. Part of that came from a particularly popular design by the older sister of one of the team members, but even our less popular shirts did well. Obviously you want some kind of original design that will sell well, but that's a little like saying "buy low, sell high" on the stock market. 
  • Cookies. A different organization we participate in uses selling cookie mixes and doughs to fundraise. We are dipping our toes into that a little right now, although I cannot report on the results for us yet. We have noticed success elsewhere with selling cookie doughs or mixes. It takes some time to create and deliver the goods, but the supplies are actually pretty cheap and yield a good return for what you sell. I've seen a similar approach done with pizzas. 
  • Share. Share on every social media platform you have, and then do it again. Specifically, I am thinking of Facebook and Instagram. If you use Twitter, tweet early and often. Same with Pinterest. Even go for Reddit, if it fits. I am not sure about LinkedIn as a platform for this, but I tried it. I am not a Snapchat user so I did not use that myself, and the same goes for Whatsapp. I probably should have. Once you have the GoFundMe or Bonfire or whatever set up, market it on social media over and over and over again. 
  • Individual emails. Email your family. Email your friends. Email everybody you know. Probably don't email your coworkers, but if they have an off-topic channel or list or forum, put it there. Don't spam people (email them repeatedly), but a single reach out shouldn't bother anybody. Ask for donations, but also ask for them to share with THEIR networks.
While it's great to score a big raise through these efforts, it's really more about eating the elephant: one bite at a time. Good luck and have fun!

Wednesday, June 13, 2012

Billerica Ward Preparedness and Self-Reliance Fair

My church congregation is having a preparedness and self-reliance fair. Lots of great resources, including nutrition, personal finance, and do-it-yourself maintenance.

Saturday, June 23rd. Tables open at 9:30 am. Classes begin at 10:15 am. Light lunch will be served. Nursery available; 18m -7.

Billerica LDS Building
70 Concord Rd
Billerica, MA 01821


Monday, September 19, 2011

Haggling for fair price on a Toyota Sienna

I purchased a new minivan a couple months ago. I hate buying cars. The whole process seems very confrontational. To speak in terms of 7 Habits, it feels very win-lose with me being the loser. That is probably why I put off making the purchase for so long. I am happy to say that I actually nailed it this time. I do not believe I took the dealer to the cleaners, but I feel good about what I paid and thing I negotiated well. I ended up paying $12,000 for a $17,000 car. Here's how:
  • My wife did a lot of research about minivans and narrowed us down to Siennas and Odysseys. By limiting the "serious" search to those two the search space became tractable.
  • I shopped at the end of the month. The dealer specifically referenced this as we were going back and forth, in that he wanted to make the sale before the end of the month.
  • I researched the prices of cars the night before, so I knew the internet price prior to stepping on the dealership. I do not know if they would have tried the higher price if I didn't know, but knowing the price on the web took the first $1000 off immediately.
  • I enumerated the available cars in our area and graphed the mileage vs. the price:
    Car Year Miles Price Town Dealer
    Sienna LE 1999 87391 $8,765 Burlington-ish Herb Chambers
    Sienna LE 2004 79136 $11,763 Woburn Woburn Toyota
    Sienna LE 2004 77313 $12,686 Woburn Woburn Toyota
    Sienna XLE 2004 87501 $12,889 Burlington-ish Herb Chambers
    Sienna 2007 74353 $13,997 Framingham Direct Auto Mall
    Sienna XLE 2004 96191 $14,555 Lexington Lexington Toyota
    Sienna 2006 76846 $14,597 Framingham Direct Auto Mall
    Sienna CE 2008 83783 $14,986 Woburn Woburn Toyota
    Sienna 2005 59732 $14,988 Woburn Woburn Toyota
    Sienna 2007 63706 $14,997 Framingham Direct Auto Mall
    Sienna XLE 2006 88967 $15,678 Burlington-ish Herb Chambers
    Sienna LE 2006 51593 $15,953 Woburn Woburn Toyota
    Sienna LE 2006 80134 $15,995 Tewksbury Tewksbury Toyota
    Sienna LE 2007 61517 $16,988 Woburn Woburn Toyota
    Sienna CE 2007 57668 $17,317 Burlington-ish Herb Chambers
    Sienna LE 2008 68134 $18,378 Burlington-ish Herb Chambers
    Sienna 2008 53970 $19,222 Lexington Lexington Toyota
    Sienna LE 2008 54830 $19,730 Woburn Woburn Toyota
    Sienna 2008 65614 $19,877 Burlington-ish Herb Chambers
    Sienna LE 2009 49274 $19,987 Burlington-ish Herb Chambers
    Sienna 2008 63053 $19,995 Tewksbury Tewksbury Toyota
    Sienna LE 2007 57863 $20,996 Hyannis Hyannis Toyota
    Sienna 2009 36132 $21,322 Burlington-ish Herb Chambers
    Sienna LE 2009 44968 $22,487 Burlington-ish Herb Chambers
    Sienna LE 2010 33505 $22,679 Hyannis Hyannis Toyota
    Sienna XLE 2007 42937 $23,782 Burlington-ish Herb Chambers
    Sienna XLE 2008 63772 $23,999 Lowell Lannan Chevrolet
    Sienna 2008 40786 $26,588 Burlington-ish Herb Chambers
    Sienna 2008 80244 $27,634 Burlington-ish Herb Chambers
    Sienna 2011 25508 $28,566 Burlington-ish Herb Chambers
    Sienna XLE-L 2008 37135 $29,834 Burlington-ish Herb Chambers
    Sienna XLE 2007 58888 $31,255 Burlington-ish Herb Chambers
    Sienna 2008 19025 $31,255 Burlington-ish Herb Chambers
    Sienna 2004 96708 ? Woburn Woburn Toyota


    This enabled me to to draw a "best fit" line and point to where the price for certain cars should be at certain mileages. The scientists among you may notice some problems with the graph, but I believe it still sends the right message. By pointing out that the price for my car was on a peak, I had some clear math to get another $4000 off.
  • Probably the most important is that I was willing to walk away. I made it very clear that I did not care if we bought a particular car at a particular time. I did not try to act like I didn't care, I really didn't care. That takes work.
Of course, this doesn't work for every dealer or every car. I could not have used my nifty graph to negotiate a price down if the price was one of the local minima. Also, the graph only allowed me to pull the price down to where it should be. I didn't get a "steal" on the car. I did walk away feeling good about it, which is worth a lot in my book.

Wednesday, January 19, 2011

$20 Amazon gift card for $10

If you have been living under the internet equivalent of a rock, maybe you have not heard. Hopefully you read this before 8:00 eastern time on Thursday, January 20th. Acting on it can get you a free, quick, and easy $10. LivingSocial has a deal today where you can buy a $20 Amazon gift card for $10. I had to look around a bit for it. My default city was Lowell, but I could not find the deal there. I had to look at Boston deals.

Amazon is an investor in the company, which is how I think they are pulling this off. There have been 1,211,962 gift cards ordered so far. Do the math: that's 12 million dollars of free Amazon credit. And there is still eight hours left! Go get your piece of the pie.

Wednesday, September 29, 2010

Start using Mint.com to manage your money today!

I really like mint. I have tried a number of other solutions and find mint to be the easiest. Plus, the price is right. Certain financial institutions sometimes have issues connecting with mint (such as Citizens Bank and ING), but normally things work great. Give it a whirl, you'll never look back.

With Mint, you can:
  • Get set up in minutes
  • See all your accounts in one place
  • Set and track your budgets & achieve your goals
  • Find hundreds of dollars in personalized savings
  • Stay safe and secure...and it's free!
View >>

Saturday, February 20, 2010

College savings and 529s

One of those things that everybody knows they should do but may still not do is backup their computer files. Another one is parents saving for the children's education. I recently just started funds for my kids, after delaying for a few years and not knowing how to start. Here are some useful resources I used during the process:
  • The college savings plan became much more concrete after listening to episode 25 of Jumping Monkeys. I listened to that podcast on the TWiT network before it went off the air. It may have been my favorite podcast, possibly behind TWiT itself. Episode 25 talked about saving for college, 529s, and had a guest from Freshman Fund. Which brings me to. . .
  • Freshman Fund is a website designed to help people save for college. In particular, it makes it easy for friends and relatives to donate to your child's fund. It also suggests plans for you based on the state where you live. For example, I live in Massachusetts, which has no tax advantage for using their fund so it makes since to pick a fund from any other state if that state's is better. I ended up NOT using this site, though, because I did not like having my kid's birthdays so publicly and easily available.
  • I started looking at 529s after hearing about them on Jumping Monkeys. They described them as "the hot new thing," but I think they aren't actually that new. 529s appealed to me because they were easy to set up, use, and maintain. It took me half an hour to set up accounts for my kids and start saving.
  • The question then becomes: "How do I pick which 529 to use?" In addition to looking on Freshman Fund, I found a number of good resources:
The important thing is to start now. Starting seemed very overwhelming to me because I thought I would make the wrong choice and lose money to fees and such. However, picking a good 529 just takes a little research and then they are super easy to set up.